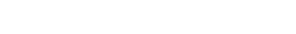

6.67%. That’s the gross rental yield on an average Karachi residential property right now, according to an October 2026 market outlook from IQI Global’s Karachi office. Compare that to the State Bank of Pakistan’s policy rate of 11.50%, and the math gets uncomfortable fast: a landlord collecting rent in Karachi today is earning nearly half what a saver gets for doing nothing except parking cash in a bank account. That gap is exactly why Karachi property rental yield has become the number serious investors are watching before they sign another sale deed.

This isn’t a reason to write off Karachi real estate altogether. It is a reason to be precise about why you’re buying, because the case for the best investment in Karachi property looks very different depending on whether you’re chasing rental income or long-term capital appreciation.
Karachi Property Rental Yield: The October 2026 Numbers
IQI’s October 2026 outlook, covering Karachi’s DHA, Clifton, Gulshan-e-Jauhar, Scheme 33, and Bahria Town Karachi, pegs the citywide gross residential rental yield at 6.67%. A premium home of 350 to 400 square yards in a prime society now sells for roughly $320,000, which works out to about Rs88.9 million at current exchange rates. The report is explicit that this yield sits “well below prevailing interest rates,” which is the single most important line in the whole study for anyone comparing property against safer alternatives.
It’s worth being precise about what 6.67% actually measures. That figure is a gross yield, calculated before deducting society maintenance charges, repair costs, property management fees, and the vacancy periods every landlord eventually faces. Once those costs are stripped out, the real net Karachi property rental yield most landlords actually pocket is closer to 4.5-5%, which makes the gap against the SBP’s 11.50% policy rate even wider than the headline number suggests.
| Benchmark | Current Rate | What It Means for a Buyer |
|---|---|---|
| Karachi gross rental yield | 6.67% | Annual rent collected as % of property value |
| SBP policy rate | 11.50% | Risk-free return available on bank deposits/T-bills |
| Premium home price (350-400 sq yd) | ~$320,000 (~Rs88.9M) | Entry cost in DHA/Clifton-tier societies |
| Yield gap vs policy rate | -4.83 percentage points | What rental income alone is giving up versus cash savings |
Why Karachi Property Rental Yield Is Lagging Interest Rates
The gap didn’t appear overnight. When the State Bank keeps its policy rate near double digits, as we covered in our IMF Pakistan Interest Rate report, bank deposits, Treasury bills, and savings certificates start competing directly with real estate for the same investor rupee. Property can’t raise its rent fast enough to keep pace with an 11.50% policy rate, so the yield gap widens even while property prices themselves stay firm or rise.
IQI’s report frames this clearly: high financing costs have been “moderating speculative activity,” pushing buyers away from leveraged flips and toward value-oriented purchases they plan to hold. Mortgage-financed buying becomes expensive when the policy rate sits above 11%, so fewer buyers are willing to borrow heavily just to catch a quick resale gain. That’s actually a healthier market structure than the leverage-driven buying sprees Pakistan has seen in past cycles, even though it makes the rental yield look unattractive on paper.
What’s Still Holding Karachi Prices Up
Despite the soft Karachi property rental yield, premium residential values in DHA and Clifton have stayed relatively steady. Three things are keeping a floor under prices even as rental returns lag, a pattern Business Recorder’s real estate sector coverage has also tracked this year:
- Limited new supply of serviced, NOC-cleared plots in established societies like DHA and Clifton.
- Continued demand from overseas Pakistanis treating property as a store of value rather than a rental business.
- Rupee depreciation risk, which makes dollar-denominated property values (like the $320,000 benchmark home) attractive to remittance-funded buyers.
Best Investment in Karachi Property Right Now: Rental Yield or Capital Gains?
Here’s the practical split. If you’re buying purely to rent out and live off that income, a 6.67% gross yield (which drops further once you subtract maintenance, society charges, and vacancy periods) is a weak return compared to an 11.50% risk-free alternative. On that basis alone, the best investment in Karachi property for a pure income-seeker right now probably isn’t Karachi property at all; it’s a government security or a bank term deposit.
But most serious Karachi property buyers aren’t actually chasing rental yield. They’re betting on capital appreciation over five to ten years, using the property as a hedge against rupee depreciation and inflation, the same logic we laid out in our Karachi Residential Plot Commercialisation report. If prices in DHA and Clifton keep outpacing inflation the way they have over the past decade, the weak rental yield becomes a minor cost of holding an appreciating asset, not the main return driver. The honest answer is that Karachi property only wins against bank deposits if you’re patient enough to hold for the capital gain, not the monthly rent cheque.
Who Should (and Shouldn’t) Buy Karachi Property for Rental Income Today
This yield gap doesn’t affect every buyer the same way, which is why a blanket “buy” or “avoid” call on Karachi property rental yield misses the point. The right move depends on your timeline and why you’re buying in the first place.
- Should buy: overseas Pakistanis sending remittances who want a rupee hedge and don’t need the rental income to live on.
- Should buy: long-term holders planning to live in the property themselves within 2-3 years, where rental yield is irrelevant.
- Should wait: investors who need the property to cash-flow immediately, since 6.67% gross (often closer to 4-5% net) won’t cover a mortgage taken at double-digit rates.
- Should wait: short-term flippers hoping for a quick resale, since the IQI report explicitly notes speculative leverage is being squeezed out of this market.
Buyers weighing Karachi against other cities should also check how Rawalpindi and Islamabad societies are pricing right now; our Bahria Town Plots NAB Auction coverage and the REIT alternative in our SECP REIT Reforms Pakistan 2026 guide both offer a way to get real estate exposure without buying and managing a physical plot directly.
Frequently Asked Questions
Is Karachi property rental yield better or worse than other Pakistani cities?
The Karachi property rental yield of 6.67% gross is broadly in line with what Islamabad and Lahore premium societies have reported this year, since all three cities are being squeezed by the same high SBP policy rate. No major Pakistani city currently offers a rental yield close to the risk-free rate.
Why would anyone buy property if bank deposits pay more?
Because property returns come in two parts: rental yield and capital appreciation. Bank deposits only give you the first kind of return (interest), with no upside if the rupee depreciates or if the property itself gains value.
Will Karachi property rental yield improve if the SBP cuts interest rates?
A rate cut would narrow the gap by making bank deposits less attractive, not by making Karachi rents rise overnight. Rental yields typically move slowly because rents adjust far less often than policy rates.
What’s a healthy rental yield for Pakistani real estate?
Most analysts consider a 7-9% gross yield healthy for Pakistani residential property in a normal interest rate environment. At 6.67%, the current Karachi property rental yield sits below that comfort zone, which is exactly why IQI’s report flags this market as one leaning on capital appreciation rather than income. Buyers who need steady monthly income should treat that 6.67% figure as a ceiling, not a guarantee, once real-world costs are factored in.
Before You Buy: A Quick Checklist
- Decide upfront whether you need rental income now or can wait years for capital appreciation; the two strategies point to different properties.
- Compare the Karachi property rental yield against the SBP policy rate and your own bank deposit rate before assuming property automatically “beats inflation.”
- If buying on a mortgage, stress-test whether rental income at 6.67% gross can realistically service debt priced off an 11.50% policy rate; for most buyers, it can’t.
- If income is the goal, compare a REIT like Naya Nazimabad’s public subscription against a physical plot before committing your full budget to one property.
Sources: IQI Global, “Pakistan Property Market October 2026: Karachi Shows Resilience as High Rates Reshape Demand” and State Bank of Pakistan, Economic Data.
Leave a Reply